ether.fi Leaves Restaking as Yields Dry Up
Ether.fi is turning weETH into a liquid staking token and moving restaking to Symbiotic. The move follows falling yields, weaker incentives, and growing attention on slashing risks in DeFi.
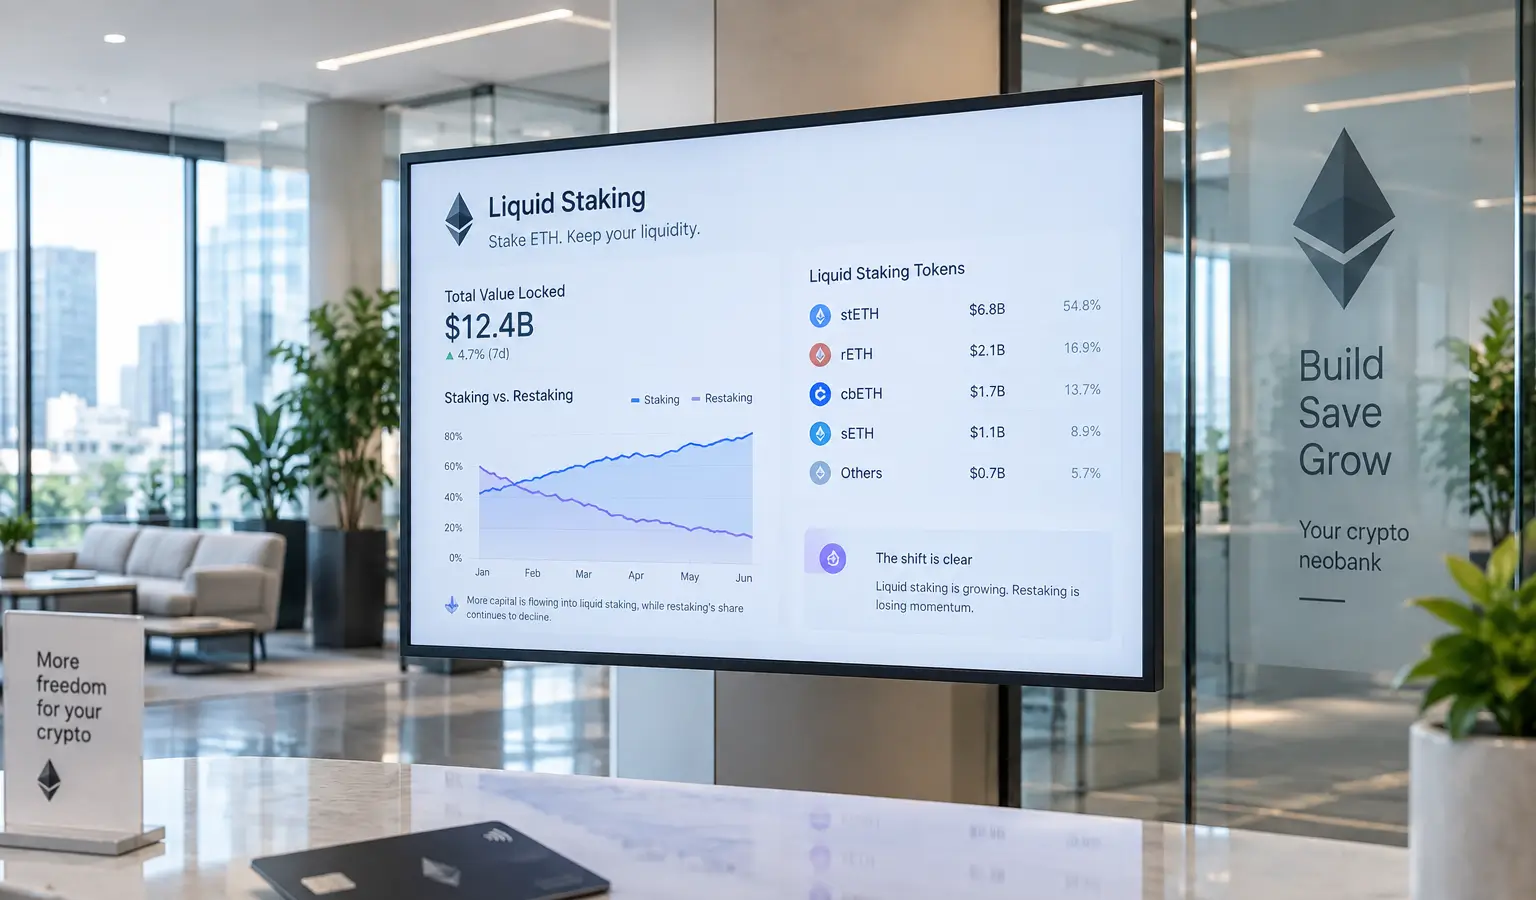
Key Takeaways
- ether.fi is removing restaking from weETH in August and turning the token into a regular liquid staking token.
- Anyone who still wants restaking will have to switch to a separate token on Symbiotic.
- The move follows disappearing yields, lower fees, and more visible risks in the restaking market.
ether.fi removed restaking from weETH in August and is now turning the token into a regular liquid staking token. Anyone who still wants restaking will have to move to a separate token on Symbiotic. The move shows how quickly the restaking hype has cooled now that yields have disappeared and the risks have become more visible.
Yields Disappeared
When ether.fi went live in 2024, ETH was automatically restaked through EigenLayer. That fit the idea behind restaking: using the same ETH not only for staking on Ethereum, but also lending it to other services that pay for it. In practice, that ended up paying less than many users had hoped.
Mike Silagadze, CEO of ether.fi, said the decision was mainly about risk and a lack of returns. According to him, there were no meaningful yield opportunities left in restaking, and stakers were also factoring in the perception of risk. The timing fits a broader cooling-off in the sector. At the end of 2024, EigenLayer was still at a peak of $19.7 billion (€17.3 billion) in locked capital, but by August 2026 that had fallen back to about $5.1 billion (€4.5 billion), according to the provided figures.
The revenue tells the same story. On September 8, the restaking category on DefiLlama stood at $10.02 billion (€8.8 billion) and brought in just $99,977 (€87,900) in fees over the previous week. The liquid staking category, with $51.87 billion (€45.6 billion), generated $27.35 million (€24 million) over the same period. Even among the bigger players, there was not much left: the five largest liquid restaking tokens together generated just $953,350 (€837,900) in combined gross profit in the second quarter of 2026.
More Risk, Less Reward
On top of that, the risks became more concrete. Slashing went live in April 2025, which means operators can actually lose part of their staked ETH if they misbehave or make mistakes. At the same time, the points programs that had previously subsidized deposits ended during 2025. That removed a major incentive to keep putting extra capital into restaking.
For European crypto followers, that matters because it shows how quickly a popular DeFi model can shift when the reward no longer outweighs the risk. The sector also still leans heavily on Ethereum. According to the provided context, about 34% of ETH supply was staked in August 2026, up from around 29% at the start of the year.
Ether.fi Looks for a New Model
Meanwhile, Ether.fi is trying to keep growing beyond restaking. The company now offers a card that lets users spend against their crypto without selling right away, a lending market on Ethereum layer-2 Optimism, and vaults. In August, it also added tokenized stocks, metals, and fiat rails and now calls itself a crypto neobank.
Silagadze said the neobank side has replaced the lost restaking revenue. According to him, 46% of monthly revenue in July came from the card, compared with 17% in January. At the same time, ether.fi's gross profit fell from $18.71 million (€16.4 million) in the third quarter of 2025 to $9.99 million (€8.8 million) in the second quarter of 2026, according to DefiLlama. That gap mainly shows how hard it has become to keep restaking alive as a standalone business model.