Bitcoin Volatility Falls, But Big Swings Remain
Bitcoin is less volatile than in 2018, but 3-sigma days keep coming back. That puts pressure on VaR models and increases the role of options and Deribit.
Key Takeaways
- Bitcoin has been less volatile on average this year than in 2018, with about 46% annual volatility versus 84% then.
- Even so, Bitcoin has already seen 10 days in 2026 with a price move of at least three standard deviations, more than the eight days seen in all of 2018.
- Risk models like VaR can underestimate the biggest losses, while options and Expected Shortfall are better at handling tail risk.
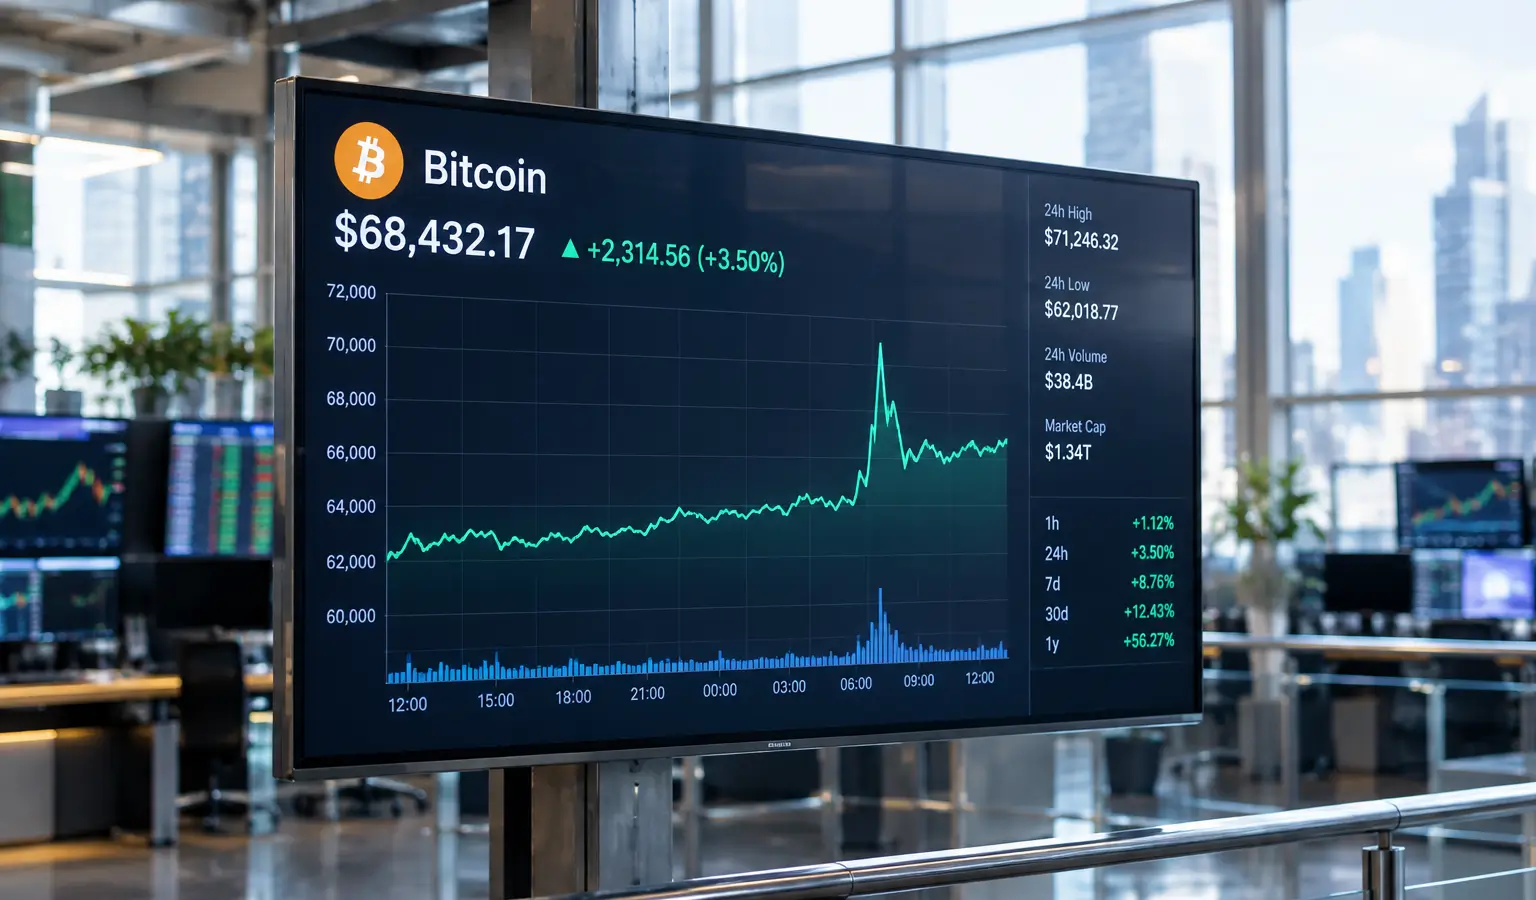
Bitcoin has been moving more calmly on average this year than in 2018, but the big swings keep coming back. According to a CoinDesk analysis, Bitcoin has already seen 10 days in 2026 when the price moved at least three standard deviations away from the recent pattern. There were eight such days in all of 2018, when Bitcoin lost 73% of its value.
Calmer Average, Sharp Swings
The analysis shows that the crypto market has not simply become less volatile. Bitcoin has an annual volatility of about 46% this year, compared with 84% in 2018, but the so-called 3-sigma moves are still striking. On average, those moves were about 7% this year, compared with roughly 10% eight years ago.
For traders, a 3-sigma day means the price moves much farther than normal based on recent trading. CoinDesk compared the daily price move with 30-day realized volatility for this. In a normal distribution, almost all moves fall within that band, which is exactly why these outliers stand out.
That mix of lower day-to-day swings and still-sharp outliers makes Bitcoin tough for standard risk models. That is especially true for models that lean heavily on recent calm in the market. Institutional investors also often look at past severe drawdowns, such as the 84% drop in 2018, to build portfolios that can better handle extreme days. That fits a broader trend in which even the latest bear market was shallower than earlier crashes, helped by spot ETFs and institutional demand.
Why Risk Models Can Fall Short
A widely used measure is value-at-risk, or VaR. It estimates how much a portfolio could lose on a bad day. If a model mostly looks at recent, calm trading, Bitcoin can seem less risky than it really is.
That is the problem: VaR says something about the chance of a loss, but not enough about how big the damage can be when the market really moves hard. That is why part of the market is shifting toward Expected Shortfall, a method that looks specifically at the worst days. Luuk Strijers, CEO of crypto options exchange Deribit, said standard VaR models do not properly account for the full tail risk.
According to him, sharp moves like these can be hedged with Bitcoin options. That fits a market where derivatives are becoming more important and where large options positions can sometimes amplify moves even further.
More Mature, But Not Quiet
Nicolas Quatravaux, head of EMEA at Paradigm, said the market has clearly become more mature. There is more institutional money, better risk management, and deeper liquidity than a few years ago. At the same time, macro shocks, leverage, and positioning still cause sudden moves.
He also pointed to the role of a growing derivatives market. On September 21, the day of Bitcoin's latest 3-sigma jump, Paradigm processed a record $6.7 billion (€6 billion) in options trading. According to Quatravaux, no desk ran into trouble this time.
For European crypto readers, that matters because it shows how quickly Bitcoin has evolved from a mostly speculative asset into a market with more institutional trading and more advanced hedging. At the same time, the core remains the same: even in a calmer market, macro news, leverage, and crowded options positions can still lead to big swings.