Clarity Act Puts Community Banks Under Pressure Over Stablecoin Rewards
Community banks fear that stablecoin rewards will pull deposits away and hurt local lending. The debate around the Clarity Act and the GENIUS Act centers on the line between rewards and interest.
Key Takeaways
- A U.S. community banker warns that the Clarity Act could put small banks at a disadvantage if stablecoin rewards are not more tightly limited.
- Nate Franzén says rewards could pull deposits out of local banks and hurt lending in small communities.
- According to Franzén, the law leaves too much room for setups through exchanges and wallets that look like interest.
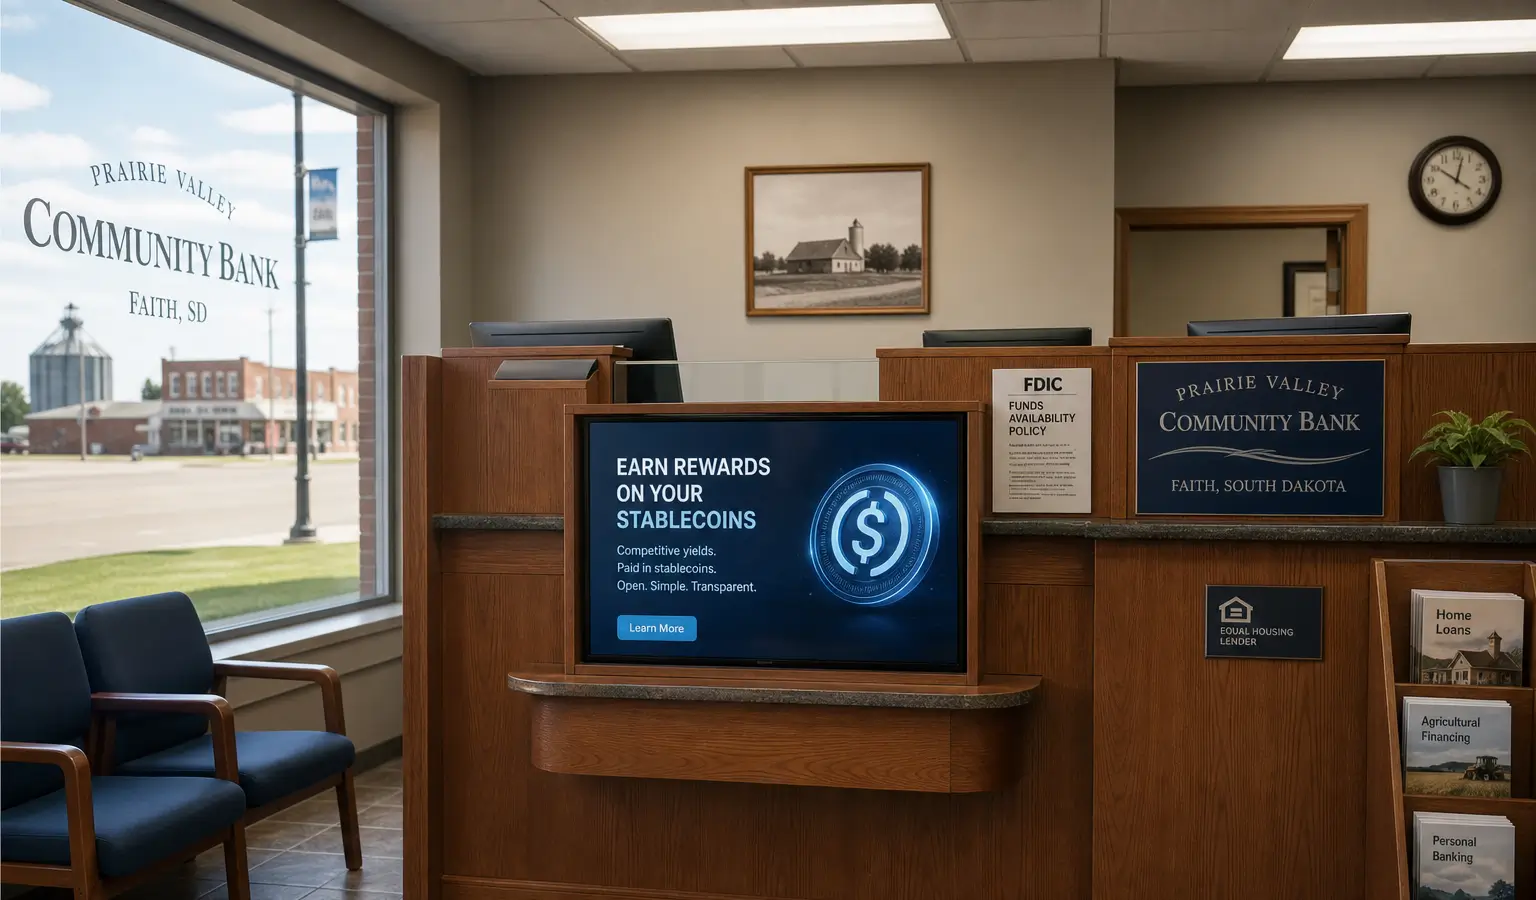
An American community banker warns that the Clarity Act could put small banks at a disadvantage if stablecoin rewards are not more tightly limited. According to Nate Franzén, a banker in South Dakota, those rewards could pull deposits away from local banks and hurt lending in small communities. He acknowledges that stablecoins can make payments faster and more international, but says the law still leaves too much room for setups that look like interest.
Why The Banking Sector Is Pushing Back
Franzén is responding to an opinion piece by Summer Mersinger of the Blockchain Association. According to him, she argued that concerns about deposit flight are mostly being pushed by big banks and were brought up too late in the legislative process. Franzén calls that view wrong and says small banks have been warning about the consequences for more than a year.
His main point is simple: if a customer takes money out of a bank account and puts it into a stablecoin, that money stays in the financial system, but no longer with the local bank. The stablecoin issuer holds reserves, often in dollars or short-term Treasuries, but the bank loses funding for local loans, according to him. In a state like South Dakota, where community banks are closely tied to agriculture, livestock, and small businesses, he says that could be felt directly.
Franzén points to figures that show the smaller banks in the state together hold about $47 billion (€40.3 billion) in deposits. The American Bankers Association estimates, according to him, that up to $4.7 billion (€4 billion) of that could shift into stablecoins if there are no clear guardrails. That could reduce lending capacity in South Dakota by as much as $3.7 billion (€3.2 billion).
Rewards And The Playing Field
The debate is not just about stablecoins themselves, but mainly about the reward structure. The GENIUS Act bans stablecoin issuers from paying interest, but according to Franzén, the Clarity Act still leaves room for exchanges and wallet providers to offer something similar through rewards. That matters because the GENIUS Act, since July 2025, is meant to prevent stablecoins from competing directly with bank deposits.
That law also requires issuers to keep 100% reserve backing with liquid assets, such as dollars or short-term Treasuries, and to publish monthly audits. That is supposed to protect consumers and increase stablecoin stability. But according to Franzén, that does not change the problem for community banks if rewards through third parties still end up looking like interest.
He calls the playing field unfair if stablecoin products can pass along yield without performing the same credit function as banks. Banks turn deposits into mortgages, agricultural loans, and working capital. Stablecoin issuers can simply hold Treasuries, according to him. As a result, he says, less credit could flow to local economies.
Why This Matters In Europe
For European crypto readers, this is especially relevant because it shows how quickly stablecoin rules can shift from innovation to market structure. Outside the U.S., the same question also comes up: when does a reward program on a wallet or exchange effectively become an alternative to a bank account? Those debates could later also affect how regulators in Europe look at stablecoins and payment products.
The U.S. debate is also bigger than one bill. In the stablecoin-yield debate, banks and crypto companies have long been clashing over whether rewards on stablecoins can pull deposits away.