Stablecoins Gain Ground With Companies and Banks
EY-Parthenon sees stablecoins and tokenized deposits showing up more and more in treasury and payment processes, especially for cross-border payments. MiCA and the GENIUS Act are giving institutions more legal clarity.
Key Takeaways
- According to EY-Parthenon, stablecoins are being used more and more in production by companies and financial institutions.
- Cross-border payments remain the main use case, especially because of slow settlement, high FX costs, and delays caused by compliance.
- Regulation in Europe and the U.S. is providing more clarity, while integration into existing ERP, treasury, and banking systems remains key.
According to new research, stablecoins have clearly moved beyond pilot projects and into real-world use. EY-Parthenon sees companies and financial institutions increasingly adding them to existing payment flows, while tokenized deposits are also gaining ground. For European readers, the key point is that this is no longer just about experiments, but about systems that are already being built into treasury and payment processes.
Companies Keep Moving Forward
In EY-Parthenon’s 2026 Blockchain Payments Survey of 521 decision-makers at companies and financial institutions, 18% of corporates say they use stablecoins in production. That is twice as many as in the 2025 survey. Tokenized deposits are growing too: 15% of corporates now report adoption.
Among financial institutions, the bar is even higher. In total, 69% say they offer stablecoin services or plan to do so within two years, compared with 30% in 2025. Among banks, 49% say they already offer tokenized deposits or plan to do so over the same period.
Cross-Border Remains the Main Driver
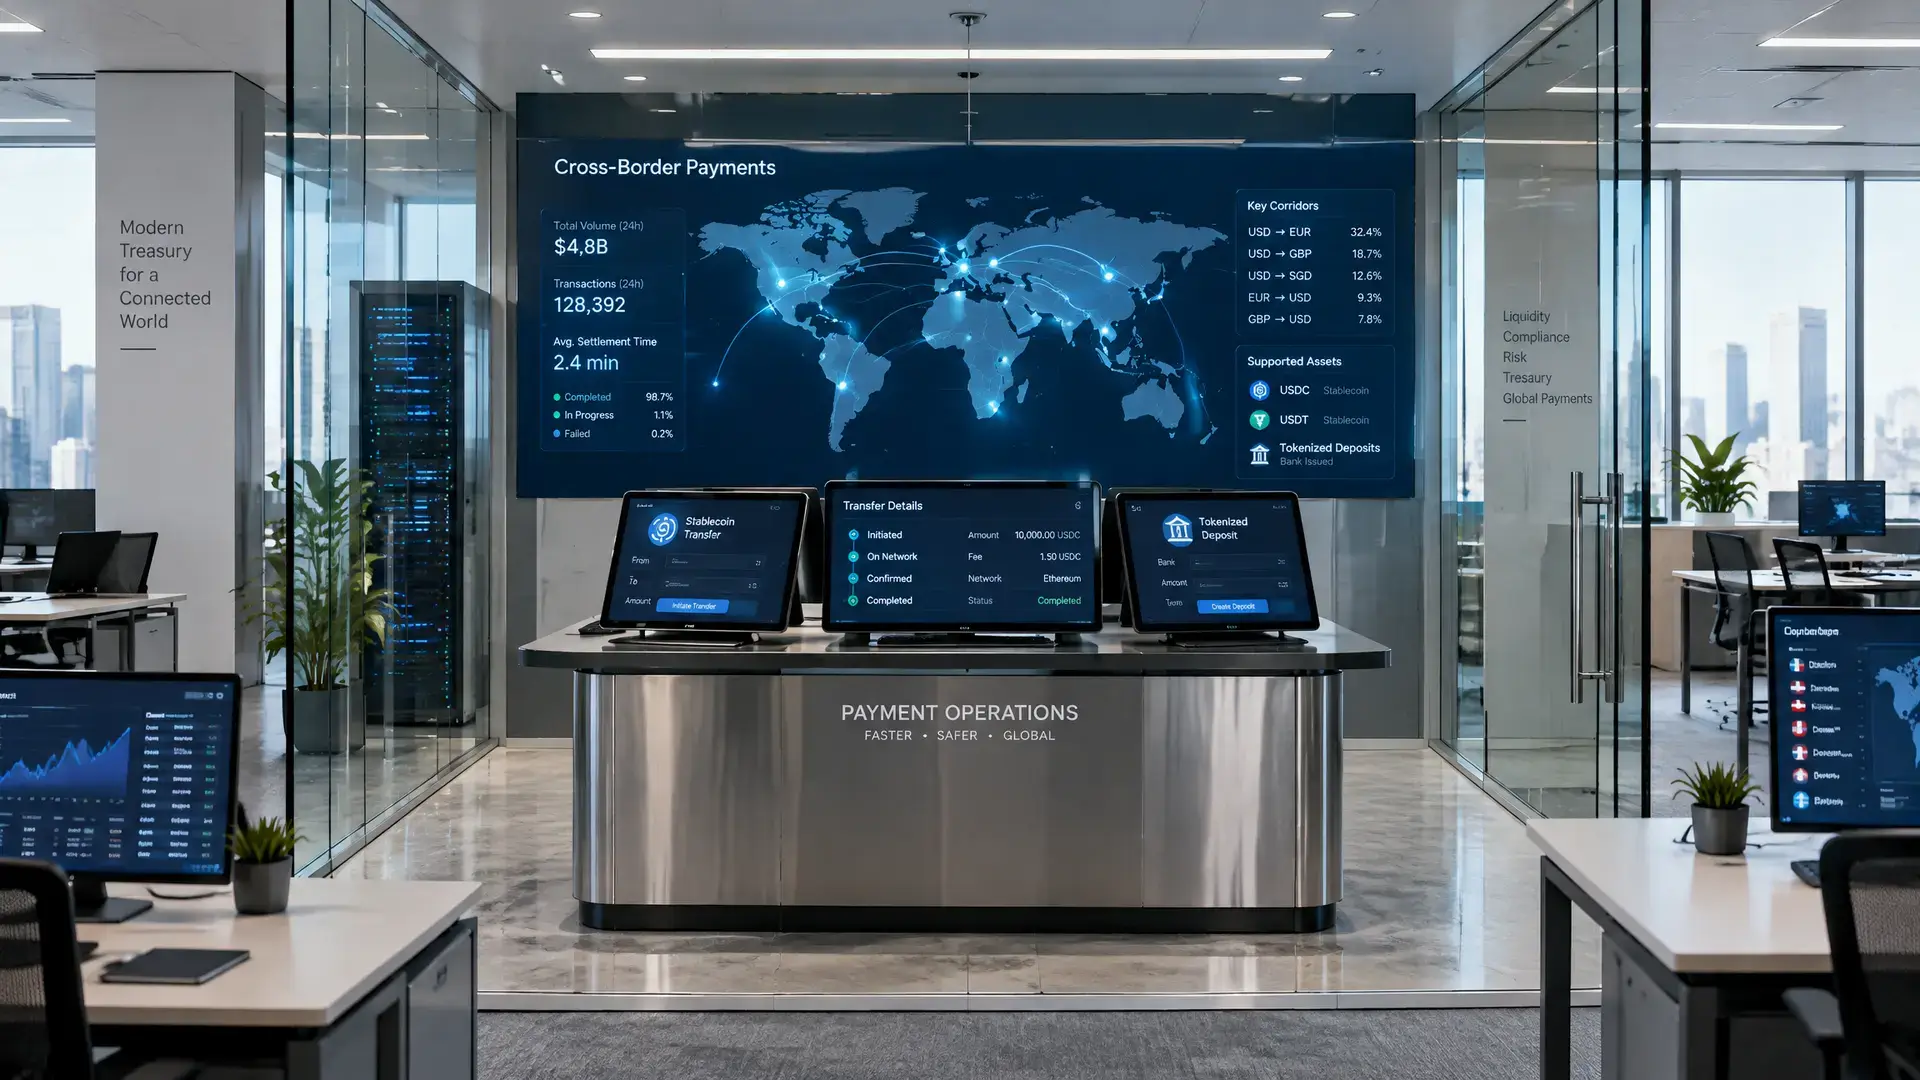
The most common use case remains cross-border business payments. Between stablecoins and tokenized deposits, 50% to 53% of respondents say they use or are exploring them for payments to suppliers abroad or for B2B acceptance.
That fits the problems companies still face. Respondents mainly point to slow processing and settlement, high FX costs or spreads, and delays caused by compliance and sanctions rules. For financial institutions, faster settlement and lower costs are the main reasons to show interest in these payment rails.
The market is still limited in size, though. One of the provided context points says stablecoins accounted for about 1% of global payment flows in 2026. That shows the growth is real, but there is still a long way to go before stablecoins become a standard part of payments.
Regulation Makes a Difference
The role of regulation is becoming more important. In Europe, MiCA set a uniform legal framework for stablecoin issuers in 2026, with strict requirements for reserve backing and regular audits. In the United States, the GENIUS Act of 2025 introduced a federal standard for payment stablecoins, with full reserve backing and regular attestations.
That clarity helps explain why institutions have become less hesitant. At the same time, the research shows that distribution is still decisive. Companies want blockchain payments built into existing ERP, treasury, and banking systems, not as a separate crypto interface. That could give existing banks and payment providers an edge, as long as they get the integration and execution right.
Competition between issuers also plays a role. Circle has long described stablecoins as digital cash for payments and capital markets, which lines up well with the shift EY-Parthenon is now seeing.