Strategy and Strive Balance Bitcoin Buying With Dividend Pressure
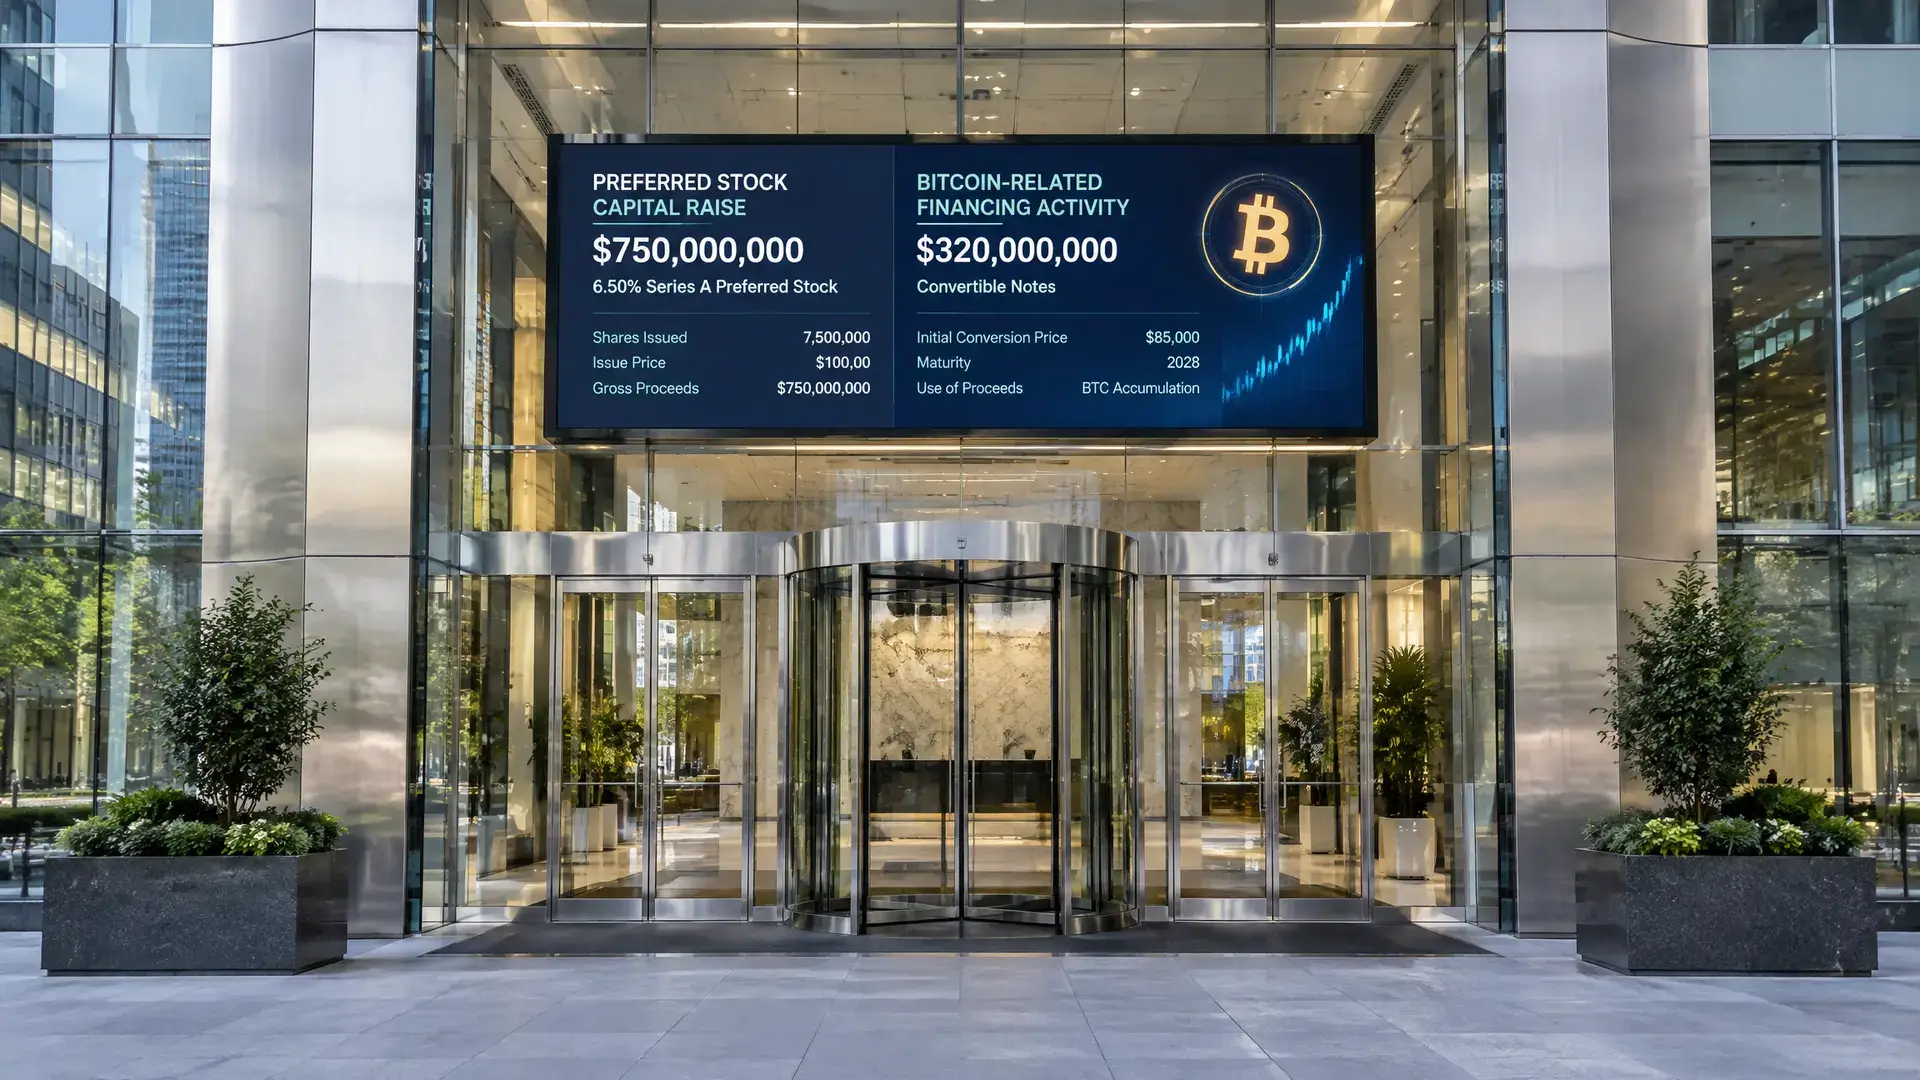
Fidelity estimates that perpetual preferred stock financed about 136,000 bitcoin over 20 months. For Strategy and Strive, that also means growing pressure from rising dividend obligations.
Key Takeaways
- Strategy and Strive finance Bitcoin purchases with perpetual preferred stock, without diluting common shares or taking on direct debt.
- According to Fidelity, those issuances financed about 136,000 bitcoin over 20 months, but they also create rising dividend obligations.
- Analysts say these yield products are bringing new demand to Bitcoin, alongside the larger inflows from U.S. spot bitcoin ETFs.
Strategy and Strive have to strike a tricky balance between continuing to buy Bitcoin and paying rising dividends on their perpetual preferred stock. According to Fidelity Digital Assets and analysts who spoke with CoinDesk, that funding model has become an important source of demand for BTC, but also a source of recurring costs.
Financing With Preferred Stock
The two crypto companies use perpetual preferred stock to raise money without diluting common shares or taking on direct debt. These investment instruments sit in the capital structure between debt and common equity, pay regular dividends, and do not carry voting rights.
According to Fidelity analyst Zack Wainwright, such issuances have financed the purchase of about 136,000 bitcoin over the past 20 months. That is more than 0.5% of Bitcoin's maximum supply. Fidelity estimates the market for bitcoin-focused preferred stock at about $12 billion (€10.7 billion), while the global bond market is worth around $150 trillion (€134 trillion).
Pressure on Strategy
Strategy is the largest corporate Bitcoin holder and therefore the main benchmark for this model. The company has five different preferred classes outstanding, and the first of them, STRK, came to market in February 2025. The more of these securities are in circulation, the higher the dividend obligations become.
James Butterfill of CoinShares said that STRC alone in 2026 had raised $7.5 billion (€6.7 billion) through the end of July. That product currently pays a variable dividend of around 12%, which makes the financing attractive for income seekers, but also creates recurring expenses for the issuer.
Alex Blume of Two Prime pointed out that products like STRC and Strive's SATA move not only with Bitcoin, but also with confidence in management and the broader capital markets. He cited STRC's drop into the $70 (€63) range at the end of June as an example of that sensitivity. Strategy preferred stock now trades around $99.40 (€89).
The broader market for Bitcoin yield products is also growing. Strive's new preferred issuance shows that smaller treasury companies are also using this model to finance extra BTC purchases.
Why This Matters for Investors
For European crypto followers, this matters because part of Bitcoin demand is coming not only from spot ETFs, but also from a growing market for yield products. Mark Palmer of StoneX said perpetual preferreds have brought Bitcoin to income seekers, a group he said ETFs did not reach. At the same time, U.S. spot bitcoin ETFs remain the bigger source of demand, with about $57 billion (€50.9 billion) in cumulative net inflows and roughly $106 billion (€94.7 billion) in assets under management.
That makes the market broader, but also more complex. If preferred issuances keep going well, they can provide extra buying power for Bitcoin. But if interest fades, it becomes harder to place new issuances, and companies may more often choose to buy back their own securities or use other ways to limit their dividend burden.