British Banks Test Tokenized Deposits Over Stablecoins
Lloyds, NatWest, and Barclays tested payments over blockchain rails inside the banking system. The trial fits the UK’s preference for bank tokens over private stablecoins, under the Bank of England’s watch.
Key Takeaways
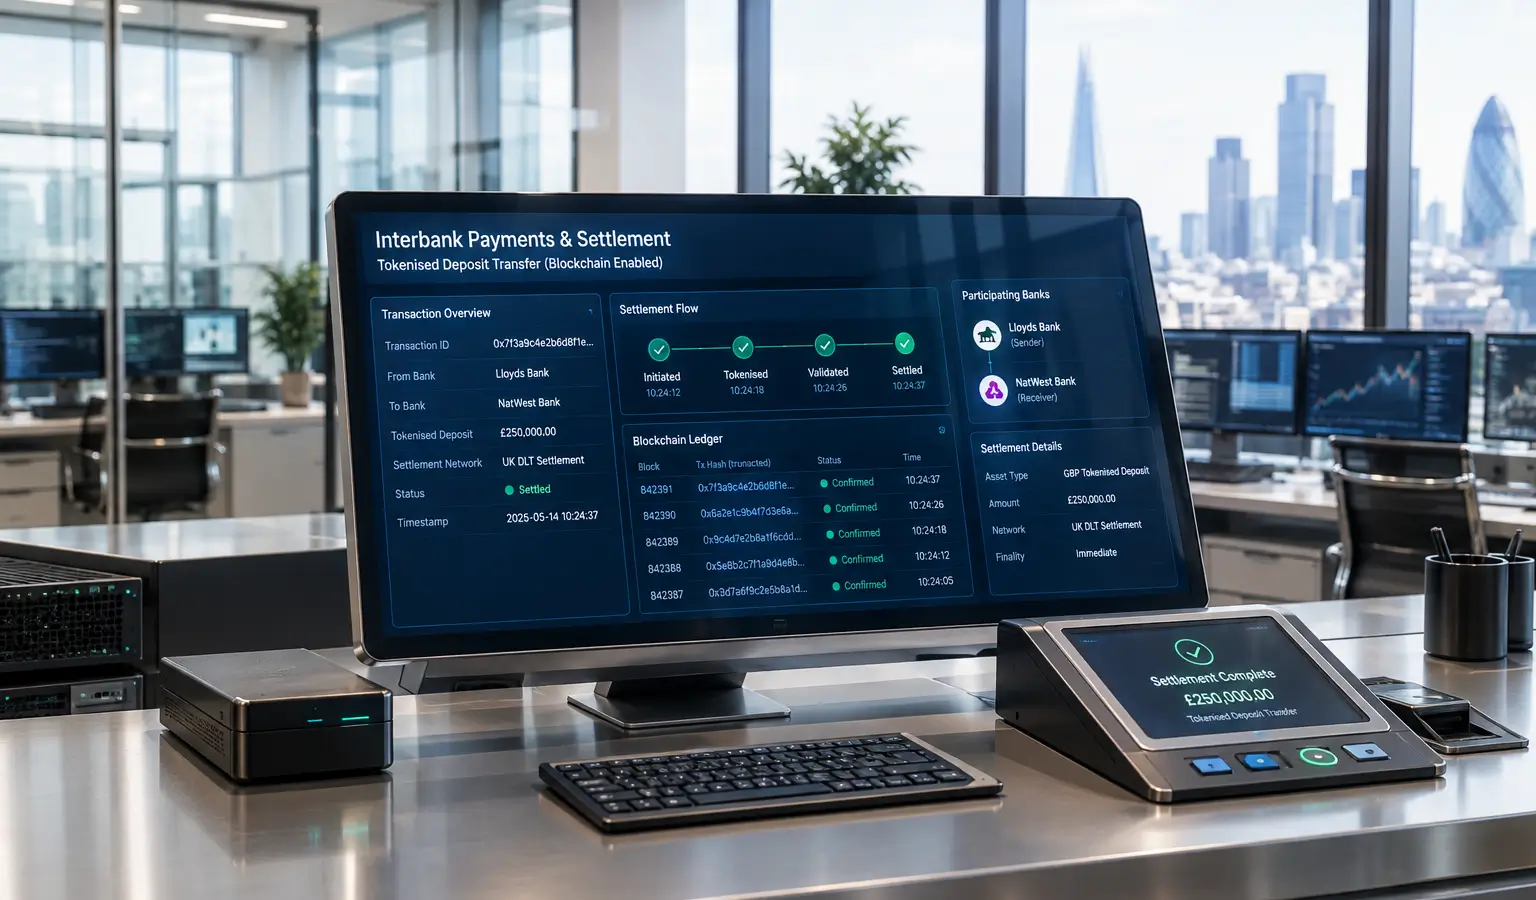
- Major British banks have completed interbank payments with tokenized deposits for the first time using blockchain rails inside the regular banking system.
- Lloyds, NatWest, and Barclays took part in the Great British Tokenized Deposit project, including mortgage transactions and simulated purchases.
- The trial reinforces the Bank of England’s preference for bank tokens over privately issued stablecoins and will continue toward digital bonds in 2027.
Major British banks have completed interbank payments with tokenized deposits for the first time. Lloyds, NatWest, and Barclays moved money over blockchain rails inside the regular banking system, instead of through stablecoins. That gives more weight to the Bank of England’s preference for bank tokens over privately issued stablecoins.
How the Trial Worked
The test was part of the Great British Tokenized Deposit project by UK Finance. Along with the interbank transfers, the banks also carried out two mortgage transactions. A separate group of banks tested a simulated purchase on a marketplace, where programmable deposits held the buyer’s money until the goods were confirmed as received.
According to UK Finance, HSBC and two other lenders also took part in a peer-to-peer transaction that mimicked an online sale. Jana Mackintosh, managing director for Payments and Innovation at UK Finance, said this kind of setup can help reduce fraud. She added that interest from abroad is growing.
Why London Is Choosing Bank Tokens
Tokenized deposits are regular bank deposits shown as blockchain tokens, but they still have the same legal status as money in an account. Stablecoins are usually issued by private companies and sit outside the banking system. The BoE has previously warned that bank-issued stablecoins could disrupt the financial system, and it still keeps an issuance cap in place, even though other restrictions were eased this year.
That approach fits the central bank’s broader policy. In June 2026, the BoE published a policy statement and a draft code for sterling stablecoin issuers, aiming to give companies more clarity and better regulate digital payment tools within the UK financial system. Pressure for stablecoin rules is also rising elsewhere in Europe; the ECB wants MiCA rule scrapped after Tether refusal as regulators take another look at reserve requirements for issuers.
What This Means for Europe
For European crypto and fintech watchers, this shows that tokenization is not just a topic for crypto companies, but also for big banks and regulators. The debate is not only about innovation, but also about what kind of digital money fits best within existing rules and financial stability. The Bank for International Settlements has also previously warned about risks around stablecoins and sees tokenization of bank deposits and government bonds as a way to modernize the financial system.
The project will now move on to setting up a company and a governance rulebook. The participating banks want to issue three digital bonds in the first quarter of 2027, which will be tradable and settled with tokenized deposits.