Cboe Explores Perpetual Futures on the VIX
Cboe is looking at a perpetual version of the VIX, a model that comes from crypto. It would bring volatility trading on Wall Street closer to the derivatives market.
Key Takeaways
- Cboe is exploring perpetual futures on the VIX, but the plan is still in an early stage.
- There are no contract specs or official filing known yet for the product.
- The move shows how crypto derivatives are increasingly finding their way into traditional markets.
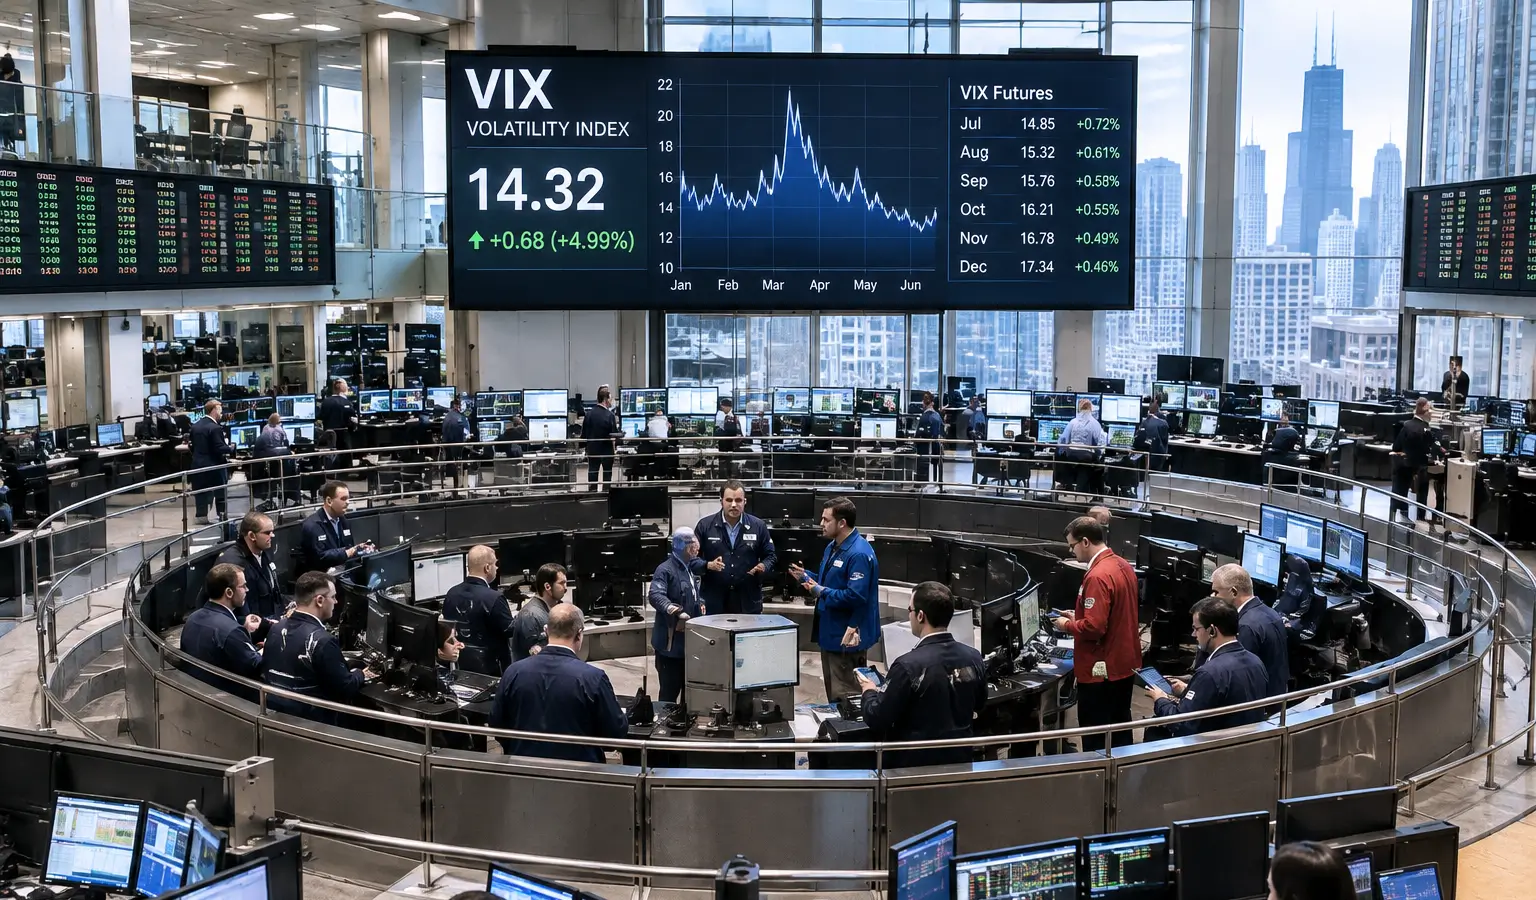
Cboe is exploring perpetual futures on the VIX, the well-known gauge for expected volatility on Wall Street. The plan is still in an early stage, and there are no contract specs or official filing known yet. Still, it shows how trading formats from crypto are increasingly finding their way into traditional markets.
What Cboe Is Exploring
Perpetual futures do not have an expiration date. In crypto, they have been popular for years because traders do not have to keep rolling into the next contract. Instead, a funding rate keeps the contract price closer to the underlying index or spot price.
With the VIX, that is interesting because the index itself is not a tradable asset but a calculation of expected 30-day volatility based on S&P 500 options. Cboe already has a broad market around the VIX with futures, options, and exchange-traded products, but a perpetual version would offer a different way to trade volatility.
Why This Stands Out
The crypto industry made perpetuals huge. By the end of 2025, decentralized exchanges together processed more than $1 trillion (€0.9 trillion) in monthly volume in this type of contract. Interest in this model is also growing outside crypto: Kalshi announced plans for perpetual futures in May 2026, and Cboe’s exploration fits into that broader shift.
According to market participants, a perpetual on the VIX could give traders more direct exposure to volatility, but costs would still remain through funding payments. Analysts at Marex Solutions pointed out that removing expiration does not automatically eliminate all hedging costs or basis risk. That is especially relevant because the VIX is not a cash asset that market makers can easily buy or sell to hedge positions.
Relevant for European Crypto Followers
For European crypto followers, this is mainly interesting because it shows how trading mechanisms from the crypto market are spilling over into major traditional exchanges. That makes the line between crypto derivatives and classic financial products smaller again. It could matter for firms active in both crypto and broader derivatives markets, especially now that volatility products are being refined even further.