Bitcoin and Ethereum Fall as Leverage Builds Again
Open interest in BTC and ETH is rising again, but funding rates and the shrinkage of Ethena’s USDe point to less extreme leverage than during the 10-10 crash.
Key Takeaways
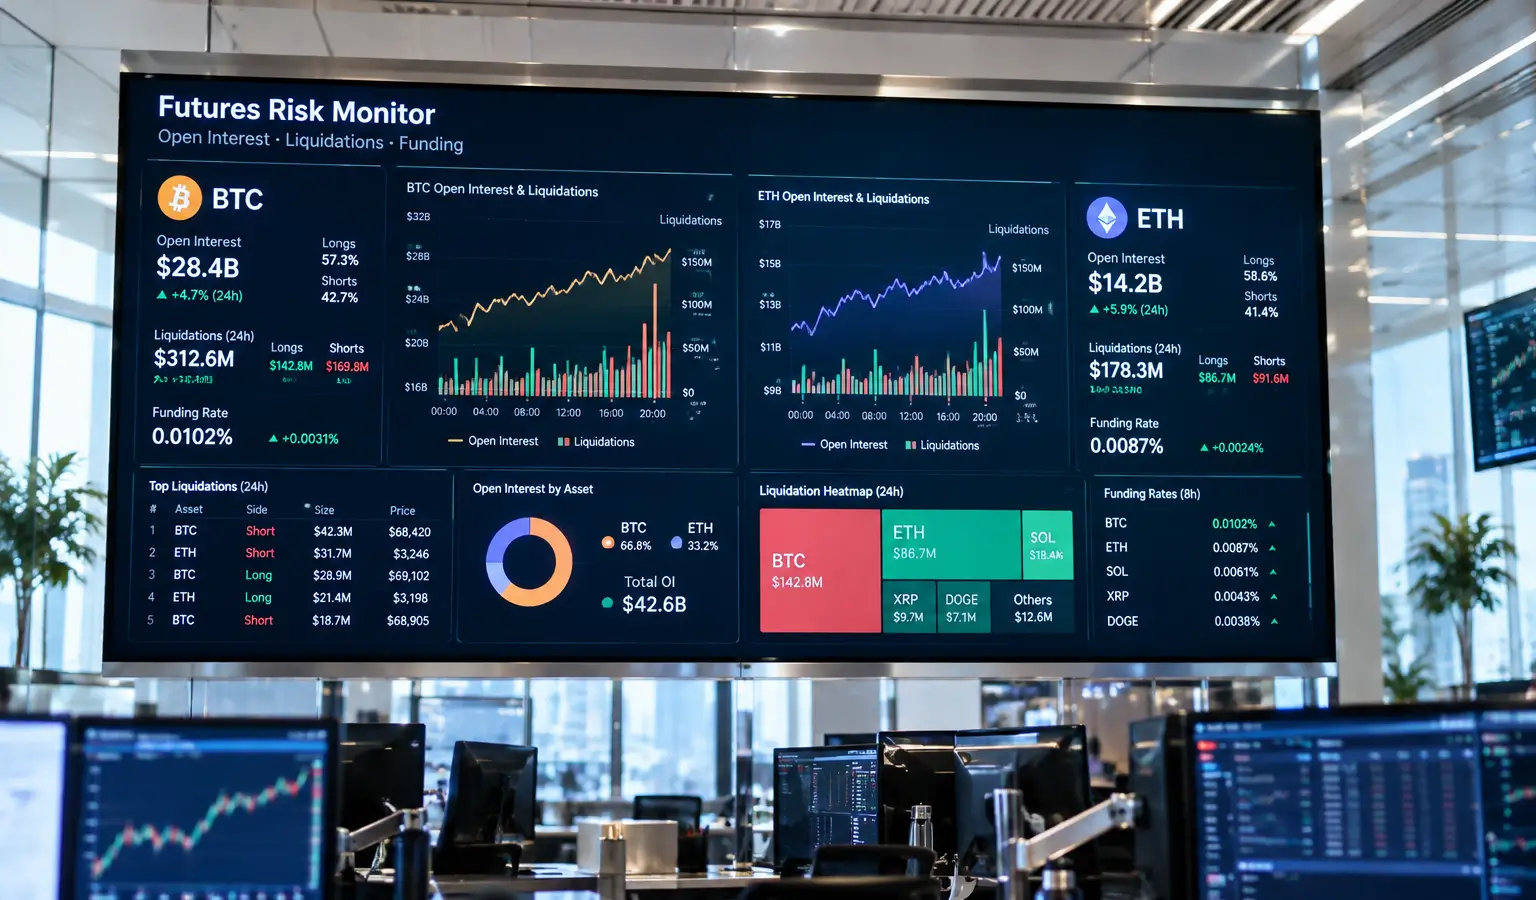
- Bitcoin fell 1.7% to around $84,100 and Ethereum 3.5%, while $403.58 million (€358 million) in long positions were liquidated in one hour.
- Bitcoin open interest rose 4.0% this week to 650,480 BTC, while Ethereum remains relatively close to its pre-10-10 level.
- Funding rates and the USDe supply are much lower than before 10-10, which means the market is less overheated than during last year’s crash.
The crypto market took another hit on Wednesday. Bitcoin fell 1.7% to around $84,100 and Ethereum dropped 3.5%, while $403.58 million (€358 million) in long positions were liquidated in one hour. That immediately raised the question of whether the market is once again heading toward a situation like 10-10, but the numbers also show clear differences from last year’s crash.
Leverage Is Back
The comparison with 10-10 mostly comes down to derivatives. Back then, the rally was fueled by borrowed money and nearly $17 billion (€15.1 billion) in longs were liquidated. Now leverage is building again, but not in exactly the same way.
Bitcoin open interest, the value of open futures positions, rose 4.0% this week to 650,480 BTC, according to CoinGlass data. Before 10-10, it rose 4.1% in five days. On a relative basis, the market is also carrying more weight again: BTC open interest is at 3.2% of market value, compared with 3.7% right before the crash. For Ethereum, that share is 10.4%, close to 11.3% at the time.
In dollar terms, the pullback looks bigger than it does in coins. Since October 10, 2025, BTC open interest has fallen 38.6% in dollars, but only 12.7% in BTC. That is mainly because Bitcoin’s price itself is lower. All in all, that means the market is once again carrying almost as much leverage for its size as it did before 10-10.
Cheaper Longs
Still, there is an important difference. The cost of keeping that leverage in place is much lower than it was last year. Funding rates show how crowded the long side is, and those payments are now far less extreme than they were before 10-10.
Before that crash, BTC and ETH funding on Binance and Bybit were above 8% annualized on 18 of the 32 trading days. This week, that happened only once in 28 days, and funding even turned negative three times. Deribit shows the same picture, with daily BTC funding at 26.9% before 10-10 versus 7.1% this week.
On top of that, an important source of extra leverage has dried up. Ethena’s USDe, a dollar token backed by hedged derivatives positions, shrank 66% to $4.99 billion (€4.4 billion), according to CoinGecko. That fits with the broader unwind in leverage since October.
Why This Matters
For European crypto investors, this matters because the market is still vulnerable to fast liquidations, but not every loss has to turn into a chain reaction right away. The Federal Reserve’s recent rate hike to 3.75% to 4.00% and higher U.S. bond yields also make risky investments less straightforward. That could affect demand for crypto, even if there is no fixed pattern showing up yet.
The broader market backdrop also plays a role: Bitcoin has recently lagged behind new records on Wall Street, which shows that the coin does not automatically move with the stronger stock rally. So the recent drop mainly shows that the market still has a lot of leverage, but it is less overheated than it was on 10-10. As long as funding stays low and open interest does not speed up further, a new mass sell-off seems less likely than it did then.